Why Your Health Insurance Cover May Not Be Enough: A Practical Guide for Indian Families
Buying health insurance is an important step towards protecting your family’s finances.
But there is a question many people never ask after buying a policy:
Is my health insurance cover actually enough?
A policy can be active, premiums can be paid on time, and you can still be financially underinsured when a major medical event occurs.
This is especially important for families in Delhi NCR, Gurgaon, Noida, Faridabad and other major Indian cities, where access to advanced healthcare can also mean significant treatment costs.
At UNC Insurance, we believe health insurance should not simply be purchased and forgotten. It should be understood, reviewed and aligned with your family’s actual protection needs.
What Does Being Underinsured Mean?
Being underinsured does not necessarily mean you have no health insurance.
It means your existing health insurance coverage may not be sufficient to protect you from a significant portion of your eligible medical expenses.
For example, imagine a family has a ₹5 lakh health insurance policy.
A major hospitalisation could potentially involve expenses significantly higher than the available sum insured.
The family technically has health insurance—but may still need to arrange additional money from savings or other sources.
This is why having health insurance and having adequate health insurance are two different things.
If you are unsure whether your current coverage is adequate, UNC’s Health Coverage Check can help you review the factors that should be considered when assessing your protection.
Why Do Families Often Stay Underinsured?
There isn’t always one reason.
In many cases, people buy health insurance based on what seems affordable at the time rather than what could realistically be required in the future.
Some common reasons include:
1. Choosing a Cover Based Only on Premium
A lower premium can look attractive.
But the cheapest health insurance policy is not necessarily the policy that provides the most suitable protection.
Coverage limits, exclusions, waiting periods, room-rent conditions, co-payment and other policy terms can materially affect the usefulness of a policy.
2. Buying Insurance Once and Never Reviewing It
Your life changes.
Your income may increase. Your family may grow. Your parents may become dependent on you. You may move to a different city or your healthcare preferences may change.
Your health insurance coverage should be reviewed when your circumstances change.
3. Assuming Employer Health Insurance Is Enough
Employer-provided health insurance can be valuable.
But depending entirely on corporate health insurance may leave gaps.
Your coverage is generally connected to your employment, and the sum insured may not necessarily reflect your family’s long-term requirements.
A personal health insurance policy can provide an additional layer of protection independent of your employer.
4. Ignoring Medical Inflation
Healthcare costs do not remain constant.
A level of coverage that appeared sufficient several years ago may not provide the same level of financial protection in the future.
This is one reason families should periodically reassess their health insurance needs rather than simply renewing the same policy indefinitely.
How Much Health Insurance Coverage Is Enough?
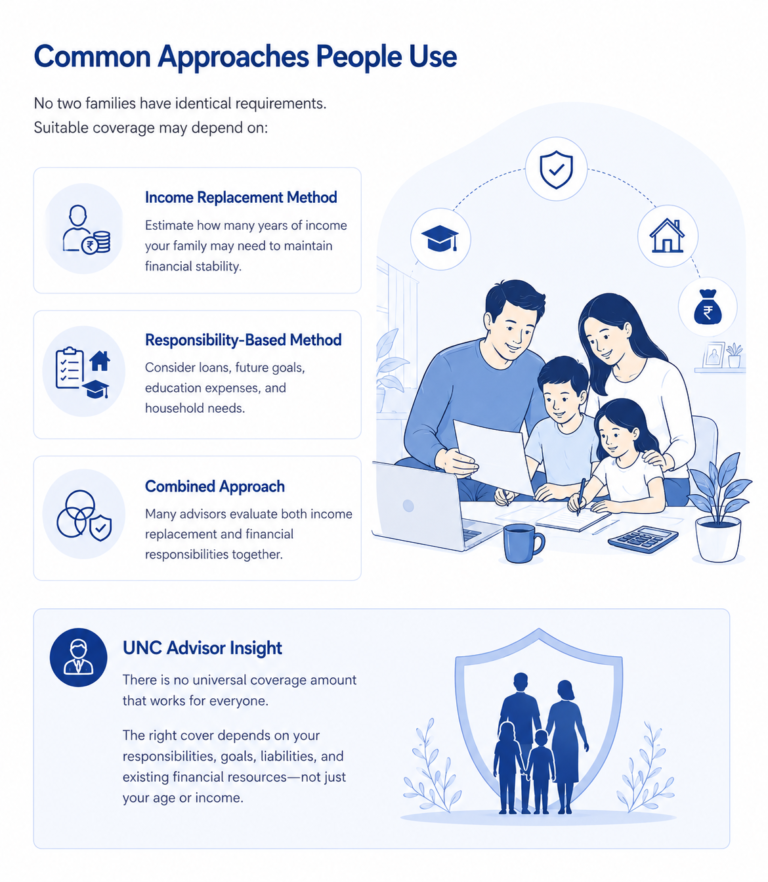
There is no universal answer.
Someone living alone with relatively few financial responsibilities may have very different requirements from a family supporting children and ageing parents.
When assessing your health insurance coverage, consider:
- Your age
- Number of family members
- Age of dependent family members
- Existing medical conditions
- Current income
- Existing savings
- Existing employer coverage
- City and healthcare preferences
- Expected future responsibilities
- Existing health insurance policies
Instead of asking:
“How much health insurance can I afford?”
also ask:
“How much medical risk can I realistically afford to carry myself?”
That is a much more useful question.
Your Sum Insured Is Not the Whole Story
A common mistake is to compare health insurance policies only by their sum insured.
A ₹10 lakh policy may look better than a ₹5 lakh policy at first glance.
But the sum insured is only one part of the policy.
You should also understand:
Waiting Periods
Some treatments and pre-existing diseases may be subject to waiting periods.
Read our detailed guide on health insurance waiting periods before comparing policies.
Exclusions
Every health insurance policy has exclusions.
Knowing what is not covered can be just as important as knowing what is covered.
UNC’s guide to common health insurance exclusions explains some of the areas buyers should review.
Room-Rent Limits
Certain policies may impose limits on room categories.
A room-rent restriction can have implications for the amount payable under a claim depending on the policy structure.
Co-Payment
A co-payment means the policyholder may have to bear a specified portion of eligible expenses.
This can reduce the amount paid by the insurer during a claim.
Restoration Benefits
Some health insurance plans offer restoration or recharge features that can restore the sum insured under specified conditions.
However, the exact conditions vary between policies.
The important point is simple:
Don’t judge a health insurance policy by one number.
Individual Health Insurance or Family Floater?
Another important decision is whether you need individual health insurance policies or a family floater.
An individual policy provides a separate sum insured for each insured person.
A family floater generally provides one shared sum insured across covered family members.
Neither structure is automatically better.
It depends on the family’s composition, ages, health requirements and overall protection strategy.
If you’re deciding between the two, read UNC’s detailed guide on Individual vs Family Floater Health Insurance.
What About Parents’ Health Insurance?
Parents require particular attention when planning family health insurance.
As people get older, healthcare requirements can become more significant, and insurance considerations can also become more complex.
Instead of automatically adding parents to an existing family floater, compare the available structures carefully.
Factors such as:
- Age
- Existing health conditions
- Waiting periods
- Premium
- Coverage requirements
- Policy limits
- Co-payment
- Network hospitals
can all influence the appropriate choice.
The objective should be to create meaningful protection, rather than simply having everyone listed on one policy.
Don’t Ignore Your Hospital Network
Your health insurance becomes most useful when you actually need treatment.
That’s why hospital network coverage matters.
If you live in Delhi NCR, for example, you may want to consider whether hospitals you are realistically likely to use are part of the insurer’s current network.
This is particularly relevant for people living in:
- Delhi
- Dwarka
- South Delhi
- Gurgaon/Gurugram
- Noida
- Faridabad
- Ghaziabad
However, network status can change, so always verify the current network list and applicable cashless conditions with the insurer.
You can also understand the difference between cashless and reimbursement health insurance claims before relying on a particular claim process.
Cashless Does Not Mean Everything Is Covered
This is an important distinction.
A cashless claim does not mean the insurer automatically pays the entire hospital bill.
Only eligible expenses covered under the policy are payable, subject to:
- Sum insured
- Policy terms
- Exclusions
- Deductibles
- Co-payment
- Sub-limits
- Waiting periods
- Other applicable conditions
You may still have to pay certain expenses yourself.
Understanding this before a hospitalisation is much better than discovering it during one.
A Simple Way to Review Your Health Insurance
You don’t necessarily need to become an insurance expert.
Start with these seven questions:
1. What is my current sum insured?
Write down the actual amount.
2. Who is covered?
Check every insured family member.
3. What are the waiting periods?
Pay particular attention to pre-existing diseases and specified treatments.
4. What are the major exclusions?
Don’t assume everything is covered.
5. Are there room-rent or treatment sub-limits?
These can influence your claim.
6. What happens if the sum insured is exhausted?
Understand whether your policy has restoration or other features that may provide additional protection.
7. Would my current coverage be sufficient for a major hospitalisation?
This is ultimately the question that matters.
UNC also provides a Hospital Expense Planner to help you think through potential healthcare expenses and the level of financial protection you may need.
Should You Increase Your Health Insurance Cover?
Not necessarily.
Increasing your coverage may make sense when your financial responsibilities or healthcare requirements have changed.
For example, you may want to review your coverage after:
- Marriage
- Having children
- Taking on a home loan
- A significant increase in income
- Becoming responsible for parents
- Changing cities
- Losing employer-provided coverage
- Discovering that your existing cover is inadequate
But simply increasing the sum insured without understanding the policy structure is not always the right answer.
Sometimes the better approach is to review the entire insurance structure.
Health Insurance Is About Risk Transfer
Think about health insurance differently.
You are not buying insurance because you expect to get hospitalised.
You are transferring a potentially large financial risk to an insurer, subject to the policy’s terms and conditions.
You pay a relatively predictable premium.
In return, the policy may protect you from a much larger eligible medical expense.
That is the fundamental purpose of insurance.
The goal is not to predict exactly what will happen.
The goal is to make sure one unexpected event does not destroy years of financial progress.
When Should You Review Your Health Insurance?
A good time to review your health insurance is before you urgently need it.
Ideally, review your policy at least when there is a significant change in your circumstances.
You should also understand the policy before renewal rather than treating renewal as an automatic payment.
If you have not reviewed your health insurance in several years, it may be worth taking a fresh look at:
- Coverage amount
- Family members covered
- Waiting periods
- Exclusions
- Network hospitals
- Co-payment
- Room-rent limits
- Restoration benefits
- Claim process
- Overall affordability
UNC Insurance: Helping You Understand Before You Buy
At UNC Insurance, we believe insurance advice should begin with understanding—not selling.
Our approach is simple:
Understand → Compare → Decide → Stay Protected.
We help individuals and families understand their insurance requirements, compare suitable options and make decisions with greater clarity.
And our role doesn’t necessarily end when the policy is purchased.
UNC also provides guidance around claim-related processes and documentation because insurance is ultimately valuable when it works during the moment you need it.
As an IRDAI Registered IMF, UNC Insurance provides human-led insurance guidance across health insurance, life insurance, pet insurance and selected protection solutions.
If you’re unsure whether your current health insurance is enough, start by reviewing your coverage rather than simply buying another policy.
Talk to a UNC Insurance advisor for guidance based on your circumstances.
Frequently Asked Questions
How do I know if my health insurance coverage is enough?
Consider your family size, age, healthcare requirements, existing savings, employer coverage, location and potential medical expenses. There is no universal coverage amount suitable for every family.
Is ₹5 lakh health insurance enough?
It depends on your circumstances. A ₹5 lakh policy may provide useful protection, but whether it is adequate depends on the insured members, healthcare requirements and overall financial situation.
Is employer health insurance enough?
Employer health insurance can provide valuable protection, but relying on it as your only health cover may create gaps, particularly if your employment or coverage changes.
Should I choose individual or family floater health insurance?
It depends on your family’s ages, health profiles, coverage requirements and budget. Neither structure is universally better.
Should I increase my health insurance every year?
Not necessarily every year. However, your coverage should be reviewed periodically and whenever your financial responsibilities or family circumstances change.
Does cashless health insurance mean I pay nothing?
No. Cashless treatment generally reduces the need for upfront payment at eligible network hospitals, but non-covered expenses, deductibles, co-payments, exclusions and other applicable costs may still be payable by the policyholder.
What should I check before renewing health insurance?
Review the sum insured, waiting periods, exclusions, room-rent conditions, co-payment, network hospitals, restoration benefits and other policy terms before renewal.
Final Thought
The question isn’t whether you have health insurance.
The better question is whether the insurance you have is capable of protecting the life you’ve built.
A policy should not simply exist in your documents or inbox.
It should make sense for your family, your responsibilities and the financial risks you are trying to protect against.
Because at UNC, we believe:
Insurance tabhi sahi, jab claim mile.
And good protection starts with understanding what you’re actually buying.
UNC Insurance
Insurance Guidance Built Around Trust, Clarity & Long-Term Protection.